Market Overview: Defining the Drone-Based Gas Leak Detection In Oil And Gas Market
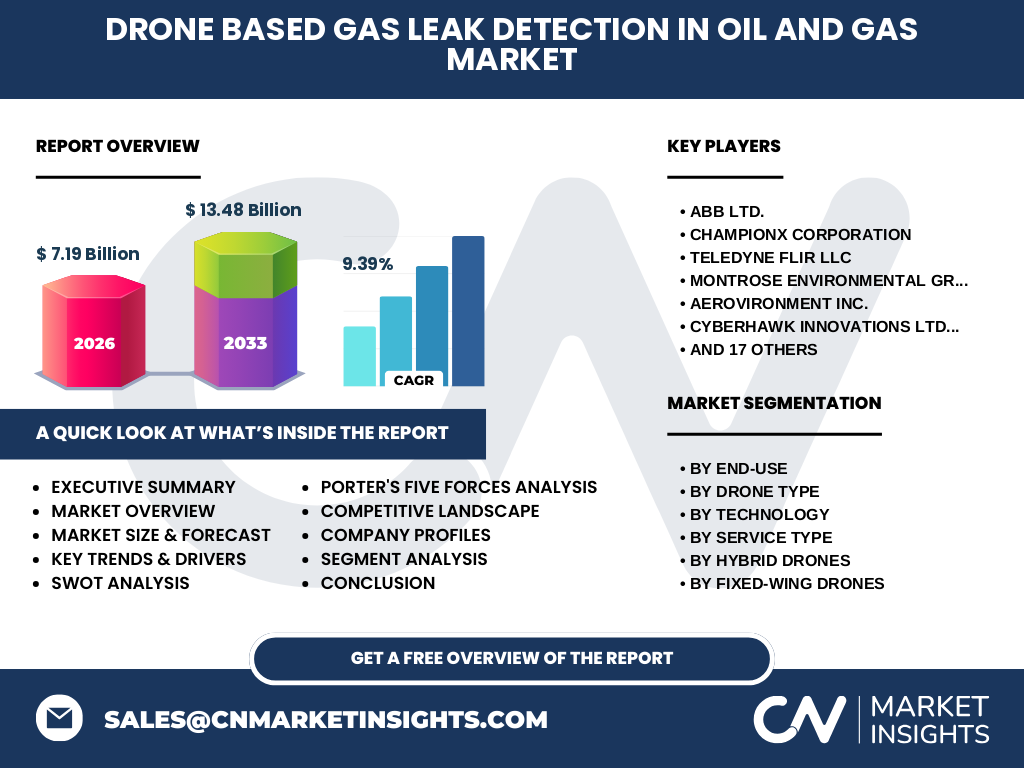
The Drone-Based Gas Leak Detection In Oil And Gas Market represents the critical intersection of autonomous aerial robotics and fugitive emission monitoring. Valued at 7.19 Billion in 2026, this sector focuses on deploying advanced payloads—such as Optical Gas Imaging (OGI) and Laser-Based Methane Detection—to identify hazardous leaks. It is an essential component for midstream and upstream asset integrity, ensuring compliance with strict global environmental mandates.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by stringent EPA and EU emission regulations, forcing operators to digitize compliance workflows. While the technical sophistication of Hybrid Drones offers a 9.39% CAGR, we observe significant constraints regarding BVLOS (Beyond Visual Line of Sight) flight permissions. Our analysis shows that firms like AeroVironment Inc. and SkyX Systems Corp. succeed by navigating these complex logistical hurdles through integrated Consultation Services.
Emerging Trends and Strategic Growth Patterns
The industry is shifting toward automated persistent monitoring. Data indicates a move away from manual, point-in-time inspections toward high-frequency, sensor-integrated workflows. Technologies like Percepto Ltd.'s autonomous hangars represent the future, allowing Multirotor Drones to conduct routine surveys without human intervention. This pivot reduces human exposure to hazardous flare sites while providing the granular data required for ESG reporting and decarbonization roadmaps.
The COVID-19 Impact and Recovery Analysis
The pandemic served as a catalyst for remote digitization. With field personnel access restricted, operators accelerated the adoption of Teledyne FLIR LLC’s thermal imaging technology for autonomous drone fleets. This necessitated a permanent shift in maintenance culture, moving away from labor-heavy manual audits to resilient, cloud-based monitoring. The recovery trajectory remains robust, underpinned by capital-intensive investments in AI-driven analytical tools that function independently of site-based human presence.
Competitive Benchmarking: Who Leads the Market?
The competitive landscape is highly concentrated yet fragmented by specialization. Teledyne FLIR LLC and ABB Ltd. dominate the high-end sensor payload segment, whereas Cyberhawk Innovations Ltd. and Aerodyne Group excel in global inspection service delivery. Our analysis indicates that players providing comprehensive, end-to-end solutions—from hardware deployment to actionable data analytics—are capturing the highest market share amidst a race toward sophisticated automation.
Executive Summary: High-Level Market Synthesis
This Drone-Based Gas Leak Detection In Oil And Gas Market report confirms a projected valuation of 13.48 Billion by 2033. Driven by the urgent need for methane mitigation, the sector is moving toward extreme high-precision imaging. Success in this market demands a symbiotic blend of ruggedized Hybrid Drone hardware and sophisticated software platforms capable of real-time gas dispersion modeling and regulatory-grade reporting.
Market Forecast: 2027 to 2033 Projections
Driven by a consistent CAGR of 9.39%, the market is set to expand aggressively from 2027 to 2033. We anticipate that as global decarbonization initiatives tighten, demand for Optical Gas Imaging (OGI) will see exponential growth. Companies that leverage Long-Range Fixed-Wing Drones for wide-area pipeline surveillance will likely outpace competitors, capturing significant market share in remote offshore and hard-to-access onshore regions.
Segmentation Analysis: Breaking Down the Industry
The market covers distinct operational segments, categorized by End-Use (Onshore vs. Offshore), Drone Type (Fixed-Wing, Multirotor, Hybrid), and Technology (OGI, Laser, IR). This breakdown is vital because offshore environments require the endurance of VTOL Hybrid Drones, while onshore gathering lines demand the agility of Quadcopters. Our analysis identifies Inspection Services as the primary revenue driver, reflecting an industry-wide preference for drone-as-a-service models over direct capital equipment acquisition.
Geographic Market Dynamics and Regional Performance
North America leads the global market, anchored by extensive shale gas operations and rigorous EPA mandates. Conversely, the Middle East is rapidly adopting drone technology to manage large-scale pipeline infrastructure. European markets are the primary incubators for advanced sensor miniaturization. The data shows that localized market constraints—such as specific aviation authority regulations in the North Sea—dictate the pace of technology adoption for offshore service providers.
Detailed Regional Review: Key Geographic Focus Areas
In North America, the focus is on high-density methane monitoring across Permian Basin assets. Encino Environmental Services LLC demonstrates how local compliance expertise drives regional leadership. In contrast, the APAC region is prioritizing rapid infrastructure expansion, favoring medium-range fixed-wing drones for vast pipeline surveying. European players remain at the forefront of regulatory-compliant sensor integration, setting global standards for emission documentation and environmental transparency.
Company Profiles: Strategic Positioning and Influence
Companies like DJI Enterprise and AeroVironment Inc. focus on scalable hardware platforms, while Montrose Environmental Group Inc. leverages drone fleets to offer complete compliance solutions. Volatus Aerospace Corp. and Terra Drone Corporation are consolidating regional service networks to offer global-standardized inspections. Our assessment indicates these firms are successfully moving from equipment suppliers to strategic partners in asset integrity, providing deep value through integrated data analytics.
Porter’s Five Forces: Assessing Competitive Intensity
The threat of new entrants is tempered by high R&D costs for sensor calibration. Buyer power is significant, as major operators (e.g., global supermajors) dictate service terms. Competitive rivalry is intensified by the rapid pace of sensor advancements. However, the bargaining power of suppliers—specifically those providing high-end infrared and laser optics—remains a critical bottleneck that defines the operational cost structure for the entire sector.
SWOT Analysis: Strategic Market Overview
Our SWOT analysis identifies regulatory alignment as a core strength, while BVLOS flight restrictions remain a significant weakness. Opportunities exist in scaling AI-driven predictive maintenance, which could transform static data into predictive insight. Threats include geopolitical shifts impacting the supply chain for drone components. Successful firms must leverage their proprietary data models to mitigate these threats, ensuring consistent performance in both onshore and offshore environments.
Value Chain Analysis: From Raw Materials to End-Users
The value chain initiates with component manufacturers (optics, micro-processors) and moves toward OEM drone integrators like Flyability SA. The flow continues through specialized service providers who perform the actual field operations, ultimately delivering analytical insights to the end-user oil and gas operators. This structure is evolving as companies seek vertical integration to maximize margins, particularly in the high-demand segment of autonomous gas leak detection monitoring.
Investment Insights and High-Potential Growth Areas
Investors should focus on firms developing autonomous sensor-to-cloud workflows. Based on our research, the highest potential lies in companies that integrate Fixed Gas Sensors with VTOL Hybrid Drones for continuous, remote site monitoring. We recommend targeting entities that hold unique regulatory approvals for autonomous flight, as these permits create a significant
Conclusion and Key Takeaways
The Drone-Based Gas Leak Detection In Oil And Gas Market is undergoing a transformative shift toward autonomous precision monitoring. With a projected 13.48 Billion valuation by 2033, the industry is moving past proof-of-concept stages. Key takeaways emphasize the necessity of high-precision sensors and AI-driven data processing. Stakeholders who prioritize long-term infrastructure integrity over mere inspection compliance will secure the strongest market position in the coming decade.
Research Methodology: How We Triangulate Market Data
Our methodology utilizes a triangulated approach: baseline estimates are derived from national trade registries, proprietary primary stakeholder interviews with Tier-1 operators, and secondary macroeconomic analysis of energy demand. By cross-referencing 13.48 Billion forecast projections against regional regulatory filing volumes and equipment delivery rates from key players like ABB Ltd., we ensure the high level of accuracy required for institutional-grade strategic planning.
Scope of the Report: Coverage and Limitations
This report covers the global Drone-Based Gas Leak Detection In Oil And Gas Market, focusing on hardware, software, and service segments. Coverage parameters include regional analysis for North America, EMEA, and APAC. While the report provides robust data on major participants and emerging technologies, it acknowledges limitations inherent in the rapidly evolving regulatory environment for BVLOS flight operations, which can cause localized volatility in regional growth projections.
Recent Developments: Market-Moving Announcements
Recent activity is defined by strategic partnerships between drone manufacturers and environmental consulting firms to offer turnkey emission detection packages. Notably, recent product launches featuring integrated laser methane sniffers for light-weight quadcopters have democratized access to high-fidelity data. These moves signal a broader market transition where even smaller, independent operators can afford the sophisticated surveillance technologies previously reserved for major integrated oil and gas enterprises.